Budget vs Actual: Turn Monthly Variances into Business Decisions
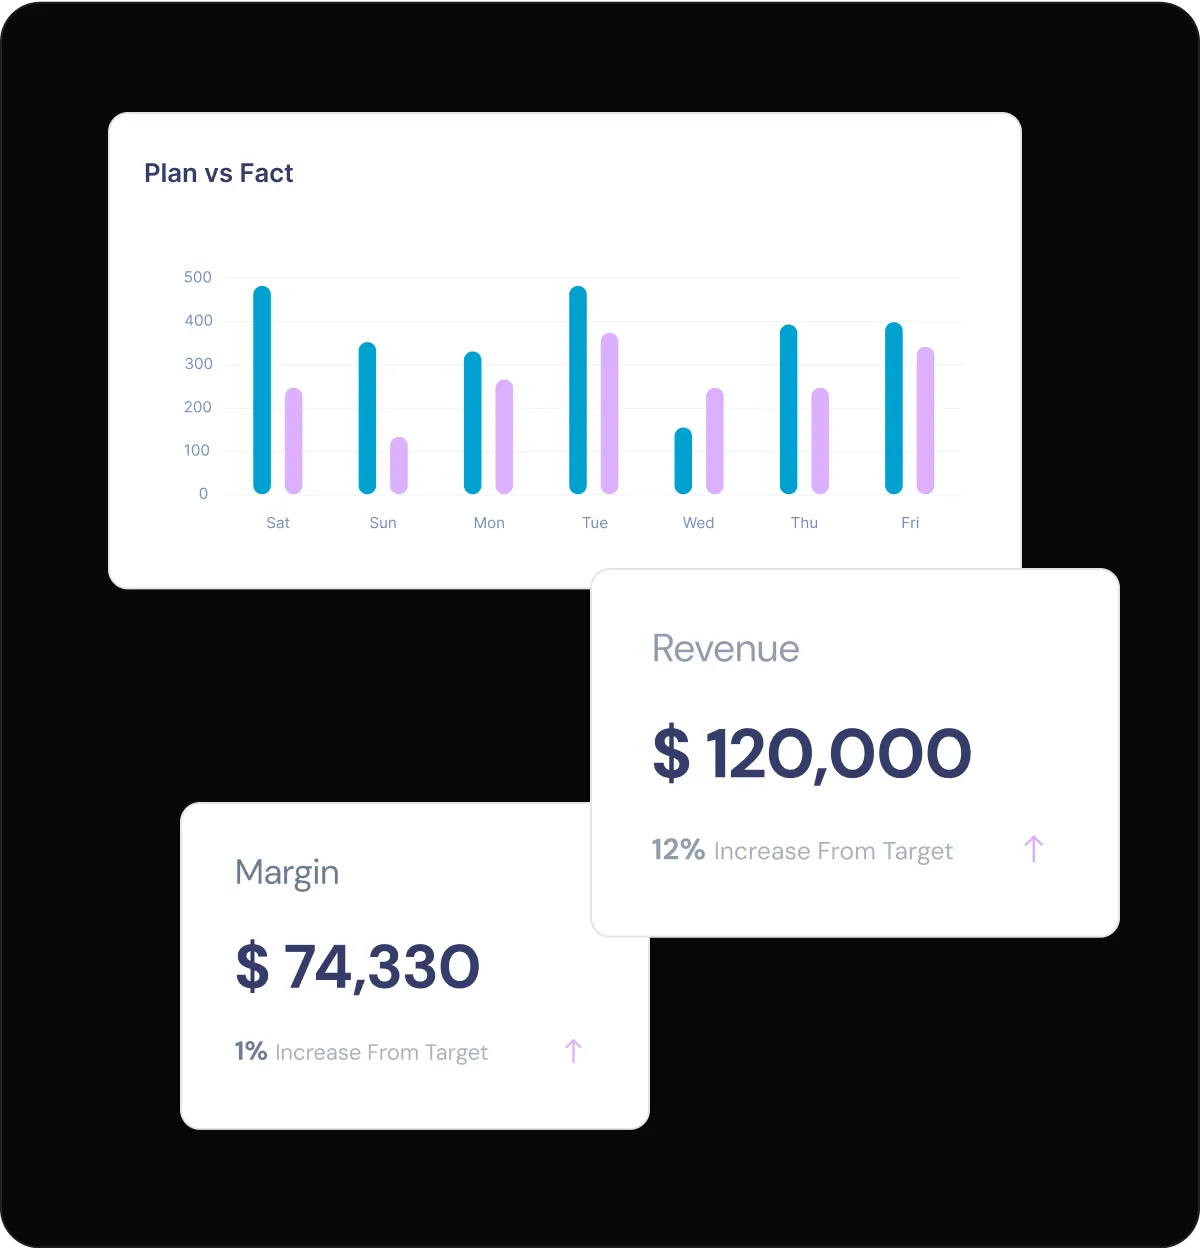

A budget review should explain what changed and what to do next. A spreadsheet full of red and green cells is only a starting point. The useful output is a short set of decisions tied to evidence, owners and dates.
Use the same period, currency, entity and account definitions for the budget and actual results. Do not compare cash receipts against a revenue budget prepared on an accrual basis without explaining the difference. Agree when the actuals are sufficiently complete for review and mark provisional numbers clearly.
Keep the original approved budget available. Maintain a separate latest forecast when expectations change. Replacing the original budget with new expectations makes it harder to see which assumptions were wrong.
A simple convention is variance = actual − budget. When the budget is a positive, non-zero amount, variance percentage can be calculated as (actual − budget) ÷ budget × 100. Treat a zero budget separately; there is no meaningful percentage change from zero. Negative budget values also need careful interpretation.
Under this convention, a positive expense variance means more spending, while a positive revenue variance means more revenue. Label the business interpretation rather than relying on the sign alone.
Suppose monthly revenue was budgeted at €100,000 and actual revenue was €90,000. The variance is −€10,000, or −10%. That calculation does not tell you whether a project slipped into next month, a client cancelled or a discount reduced the price.
In a separate illustrative expense example, contractor costs were budgeted at €20,000 and reached €26,000: +€6,000, or +30%. The overspend might reflect additional delivery volume, a higher rate or unplanned rework. Each explanation calls for a different response.
Set review thresholds that fit your business. A small percentage on a large cost line may matter more than a large percentage on a minor subscription. Discuss both financial size and operational consequences.
Instead of “revenue below plan,” write a specific note such as: “One delivery milestone moved into next month; the project owner will confirm acceptance timing by Friday.” Use such wording only when the underlying facts support it. If the cause is unknown, assign an investigation rather than inventing an explanation.
Finish the review by updating the forecast where needed and recording decisions separately from observations. At the next meeting, check whether the actions happened and whether the assumptions held.
Finance Therapy offers plan/fact analysis tools. Book a call to discuss a reporting routine that connects your monthly figures with operating decisions.
We not only develop our products, but also help with financial management:


Explore our latest insights, trends, and expert tips to optimize your business finances
Leave a request and our team will find the best financial automation solution for you!